You just landed a contract that could change your business. The timeline is tight, the scope is big, and the only thing standing between you and a major payday is the equipment you don’t have. Sound familiar? For contractors and construction business owners, this situation happens more often than you’d think. Construction equipment financing is designed to solve exactly that problem, and when used, it can be one of the smartest moves you make for your business.
What Is Construction Equipment Financing?
Construction equipment financing is a funding solution that lets you get the equipment you need now and pay for it over time. Instead of wiping out your working capital with one purchase, you spread the cost across manageable payments.
The equipment itself typically acts as collateral. That means lenders are often more flexible on credit requirements than they would be with an unsecured loan. This can be a big deal for smaller or newer construction companies.
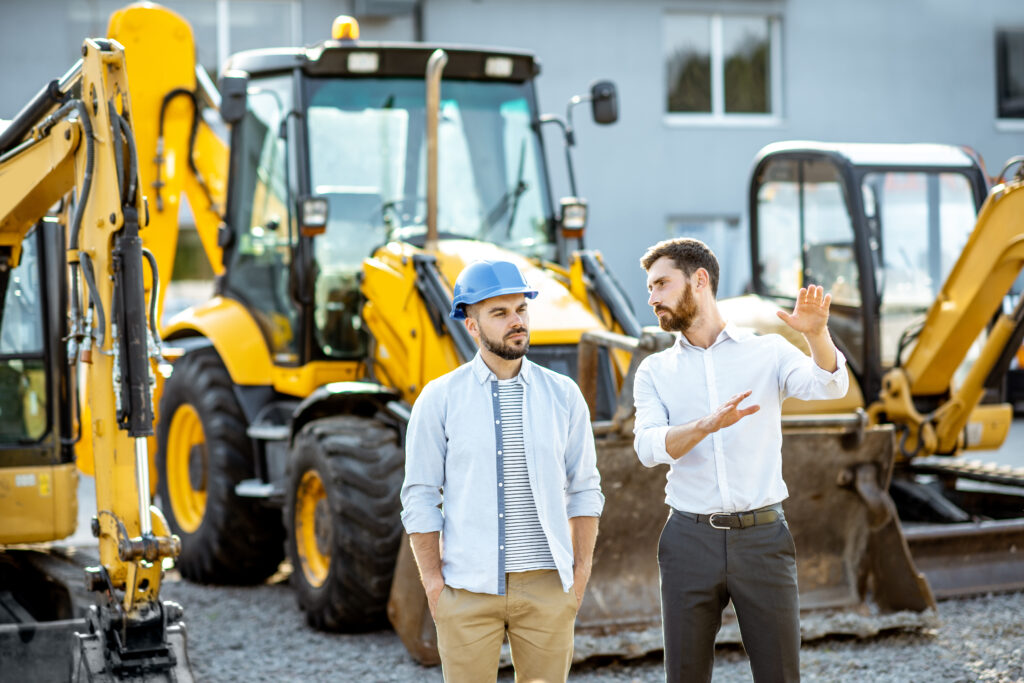
Construction equipment finance can cover a wide range of assets used on the job site. Here are some common examples:
- Excavators, backhoes, and bulldozers
- Dump trucks, flatbeds, and work vehicles
- Cranes, lifts, and scaffolding systems
- Skid steers and compact track loaders
- Generators, compressors, and drilling equipment
If it helps you complete a job, there is a good chance it can be financed.
Equipment Loans vs. Equipment Leases
There are two main options for construction equipment finance. With a loan, you borrow funds to purchase the asset and own it once the loan is repaid. With a lease, you pay to use the equipment for a set term, sometimes with the option to buy at the end.
Loans make sense for equipment you plan to use long-term. Leases can be a better fit when you want flexibility to upgrade. A knowledgeable lender can help you figure out which option works best for your situation.
What Are the Benefits of Financing Construction Equipment?
Construction equipment does not come cheap. A mid-range excavator can run anywhere from $100,000 to $500,000 new. A construction-grade dump truck can easily top $150,000. Paying that amount of money out of pocket, especially when you have payroll, materials, and overhead to cover, puts serious strain on cash flow.
Keep Your Cash Where It Belongs
Cash flow is the heartbeat of any construction business. When you put a large amount of capital into one equipment purchase, you limit your ability to take on new projects or cover unexpected costs. Construction equipment financing lets you hold onto your working capital while still getting the tools you need to do the job.
Win More Jobs
Better equipment means you can bid on larger contracts. If your competitors show up with newer, more capable machinery, they have a real advantage. Financing levels the playing field without requiring you to drain your savings first.
Potential Tax Benefits
Depending on how your financing is structured, you may be able to take advantage of Section 179 of the IRS tax code, which allows qualifying businesses to deduct the full purchase price of financed equipment in the year it goes into service. Always talk to your tax advisor to see how this applies to your specific situation.
Build Your Business Credit
Every on-time payment on a construction equipment loan works in your favor. A stronger credit profile opens doors to better terms down the road, whether that is a larger equipment line, a business line of credit, or an SBA loan for a bigger expansion.
Does My Credit Score Matter When Applying?
It matters, but it is not the whole picture. Because the equipment typically serves as collateral, companies offering construction equipment financing can be more flexible than traditional banks. Factors like your business revenue, time in operation, and the value of the equipment being financed all play a role in the decision. If your credit history is less than perfect, you may still have other options available.
Choosing the Right Construction Equipment Finance Company
Not all lenders are the same, and in construction, the wrong lender can slow you down. Here are a few things to look for when comparing your options.
Speed matters. Projects do not wait, and neither should your financing. Look for lenders that can approve and fund quickly, often within a few business days.
Transparency is just as important. Confusing terms and hidden fees are red flags. A good lender explains every number clearly and makes sure you know exactly what you are agreeing to before you sign.
Flexibility is also key. Can the lender work around your cash flow, including the seasonal slowdowns that many construction businesses deal with? The best construction equipment finance companies look at how your business actually operates, instead of trying to fit you into a set program.
Ready to Move Forward? Here Is How Sandbar Fund Can Help
We know what it feels like to have a big opportunity in front of you and not have the proper equipment to take advantage of it. Our equipment financing program around speed, flexibility, and honest communication with no surprises along the way.
At Sandbar Fund, we offer financing options with flexible repayment terms, a streamlined application process, and strong approval rates, even for businesses that have faced credit challenges in the past. We look at the full picture of your business, not just a number on a report.
Whether you are a sole contractor looking to add one piece of equipment or a growing operation ready to upgrade your entire fleet, we structure construction equipment financing to meet your goals. Apply now or contact our team today to get started. The next big job shouldn’t have to wait.
Construction Equipment Financing FAQs
What is construction equipment financing?
It is a funding solution that allows construction businesses to acquire equipment now and pay for it over time. The equipment typically serves as collateral, making approval easier than many traditional loans.
What types of equipment qualify for construction equipment finance?
Most equipment used on a job site qualifies, including excavators, dump trucks, cranes, skid steers, and generators. If it helps you complete a job, it can likely be financed.
Do I need great credit to qualify?
Not necessarily. Lenders consider factors like revenue, time in business, and equipment value alongside credit history. Many construction businesses with less-than-perfect credit can still qualify.
Is it better to get a loan or a lease for construction equipment?
Loans are better for the equipment you want to own long-term. Leases work well when you anticipate needing to upgrade regularly or want lower monthly payments. Your lender can help you decide.
How fast can I get approved?
Many alternative lenders can approve and fund within a few business days. Having your bank statements and application ready in advance helps speed up the process.
Can a newer construction company qualify?
Yes. Many lenders, including Sandbar Fund, work with businesses with shorter track records, focusing on revenue and equipment value rather than years in business alone.