Opening a dental office, buying an existing one, or upgrading your equipment can be a big upfront expense. Financing a dental practice helps many dentists make these moves happen. Luckily, more funding options are available today than ever before.
Why Do Dentists Use Financing?
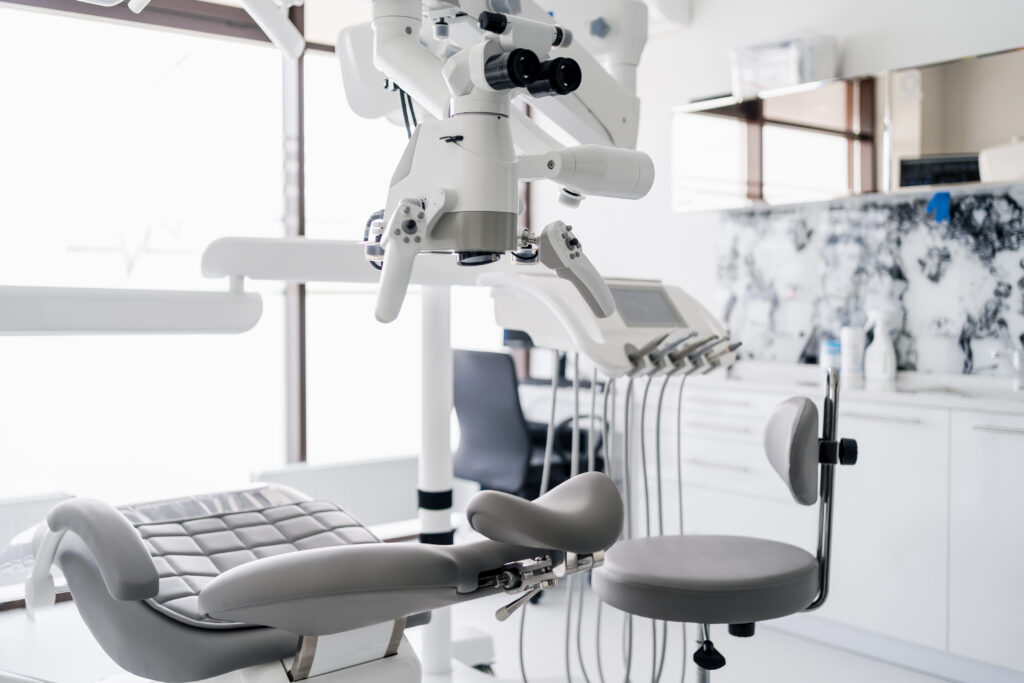
Dental practices come with big price tags. A new office needs equipment, dental chairs, X-ray machines, and sterilization tools, plus the buildout costs for plumbing and electrical work. Buying an existing practice means paying for the client base, equipment, and goodwill the previous owner built.
Financing a dental practice lets you spread these costs out over time instead of draining your savings in one shot. It also gives you room to keep cash on hand for payroll, supplies, and the everyday costs of running a business.
Are There Different Options for Financing a Dental Practice?
Yes. Different lenders offer different products, and the right fit depends on what you are trying to do. Some dentists need funds to buy a complete practice. Others just need help covering a new piece of equipment or smoothing out cash flow during a slow month.
Here are the most common options dentists turn to:
- SBA loans
- Traditional business loans
- Equipment financing
- Business lines of credit
- Merchant cash advances
- Collateral loans
SBA Loans for Dental Practices
SBA loans are a popular choice for dentists buying or starting a practice. These loans come with lower interest rates and longer repayment terms than many other options, which can make monthly payments easier to manage. The tradeoff is that the application process usually takes longer and requires more documentation.
Traditional Business Loans
A business loan gives you a lump sum upfront, which you pay back over a set term with fixed payments. This works well for a specific expense, like buying an existing practice or covering the cost of a full office buildout. Since the payments are predictable, a loan can make it easier to plan your monthly budget.
Equipment Financing
Dental equipment is expensive. Equipment financing lets you spread the cost of chairs, imaging tools, or sterilization systems over time instead of paying the full amount upfront. This keeps your working capital available for other parts of the business.
Equipment Leasing
Dental technology changes fast, and equipment that feels current today can be outdated in just a few years. Leasing lets you regularly upgrade to newer models without committing to a large purchase each time. This can be a smart option if you want to keep your practice equipped with the latest tools while keeping monthly costs predictable.
How Does a Dental Practice Loan Work?
A dental practice loan works like most business loans. You apply, a lender reviews your financials, and if approved, you receive funds that you repay over an agreed term with interest. Details vary by lender and loan type, but most dental practice loans focus on a few key factors.
Lenders typically consider:
- Your credit history and score
- Time in business, if you already own a practice
- Projected or current revenue
- The purpose of the loan
- Any collateral you can offer
Dentists with an established practice and steady patient revenue often qualify more easily, since lenders can see a track record of income. New dentists or those buying their first practice may need to lean more on projected revenue and a solid business plan.
What If Your Cash Flow Changes?
Not every dental practice expense fits neatly into a lump sum. Payroll, supply orders, and slow months can create gaps that a term loan is not built for. In these cases, a business line of credit can help. You draw what you need, pay interest only on that amount, and the credit becomes available again as you repay it.
Some practices also use a merchant cash advance for faster access to funds, especially when a lender’s turnaround time matters more than getting the lowest rate. This option works differently than a loan, since repayment is often tied to a percentage of future revenue rather than a fixed monthly payment.
Using Collateral to Improve Your Terms
If you own equipment, real estate, or other business assets, a collateral loan may help you access more funding at a lower interest rate. Offering collateral reduces the lender’s risk, which can help you negotiate better loan terms.
Choosing the Right Finance Option
Choosing how to finance a dental practice comes down to your specific goal. Buying a practice or funding a major buildout usually calls for a larger loan with a longer term, like an SBA loan or traditional business loan. Upgrading equipment often makes more sense with equipment financing, since the loan is tied directly to the asset. Managing everyday cash flow usually fits better with a line of credit.
It also helps to get your financial records in order before you apply. Lenders want to see clean books, a clear picture of your revenue, and a solid understanding of what you plan to do with the funds. Taking time to prepare before you apply can speed up the entire process.
Ready to Finance Your Dental Practice?
We know that financing a dental practice can feel like a lot to navigate on top of running a busy office. At Sandbar Fund, our team works with dental practice owners to review their goals, walk through loan options, and match them with funding that fits their situation, whether that means an SBA loan, equipment financing, or a line of credit. We keep the process straightforward, so you can spend less time on paperwork and more time with your patients.
If you are ready to explore your options, apply now or contact our team to talk through what fits your practice best. We will help you find a funding path that supports your practice.

Financing a Dental Practice FAQs
What is the best way to finance a dental practice?
There is no single best option. SBA loans and traditional business loans work well for buying a practice or funding a large project. Equipment financing fits equipment purchases, and a line of credit helps manage everyday cash flow. The right choice depends on your specific goal.
How much does it cost to finance a dental practice?
Costs vary widely based on whether you are starting a new practice, buying an existing one, or upgrading equipment. Loan amounts, interest rates, and terms depend on the lender, your credit profile, and how much funding your specific plans require.
Can new dentists qualify for a dental practice loan?
Yes. New dentists may need to rely more on projected revenue, a solid business plan, and personal credit history since they do not yet have an established track record. Some lenders also weigh collateral or a co-signer more heavily for newer practices.
What documents do I need to apply for financing?
Most lenders ask for financial statements, tax returns, and information about your practice or business plan. Requirements vary by lender and loan type, so it helps to have your records organized and ready before you start the application process.
Is an SBA loan better than a traditional business loan for a dental practice?
SBA loans often offer lower interest rates and longer repayment terms, but the application process typically takes longer. A traditional business loan may fund faster. The better option depends on your timeline and how much flexibility you need.
Can I use financing to cover both equipment and cash flow needs?
Yes. Many dentists combine funding types, using a loan or equipment financing for larger purchases and a line of credit for day-to-day fluctuations. Using more than one option together can offer more complete coverage for different needs.
Do I need collateral to finance a dental practice?
Not always. Some loan types do not require collateral, though offering it can sometimes help you access more funding or a lower interest rate. Options like equipment financing may use the equipment itself as collateral instead.